How Does Blockchain Work? A Complete Beginner-Friendly Guide
When people hear the word “blockchain,” they often think about Bitcoin, cryptocurrency, trading, or complicated computer code.
Blockchain is often mentioned alongside Bitcoin, cryptocurrency, NFTs, and Web3. Because of this, many people assume that blockchain is only related to digital currencies. In reality, cryptocurrency is just one of the many ways blockchain technology can be used.
At its core, blockchain is a system for storing, verifying, and sharing information across a network of computers. Instead of keeping all records inside one central server controlled by a single company, a blockchain can allow many computers to maintain and verify the same record. The technology may sound complicated at first, especially when terms such as cryptography, nodes, hashes, mining, validators, and consensus are introduced. However, the basic idea becomes much easier to understand when it is explained through familiar examples.
What Is Blockchain?
Blockchain can be described as a digital record book that is shared across multiple computers. In a traditional banking system, the bank maintains its own private database. When one person sends money to another, the bank checks whether the sender has enough money, approves or rejects the transaction, updates the account balances, and stores the new information on its server. The bank acts as the central authority responsible for maintaining the records.
A blockchain can work differently. In many blockchain networks, no single company or organization controls the complete record. Instead, several computers connected to the network maintain copies of the same information. These connected computers are called nodes.
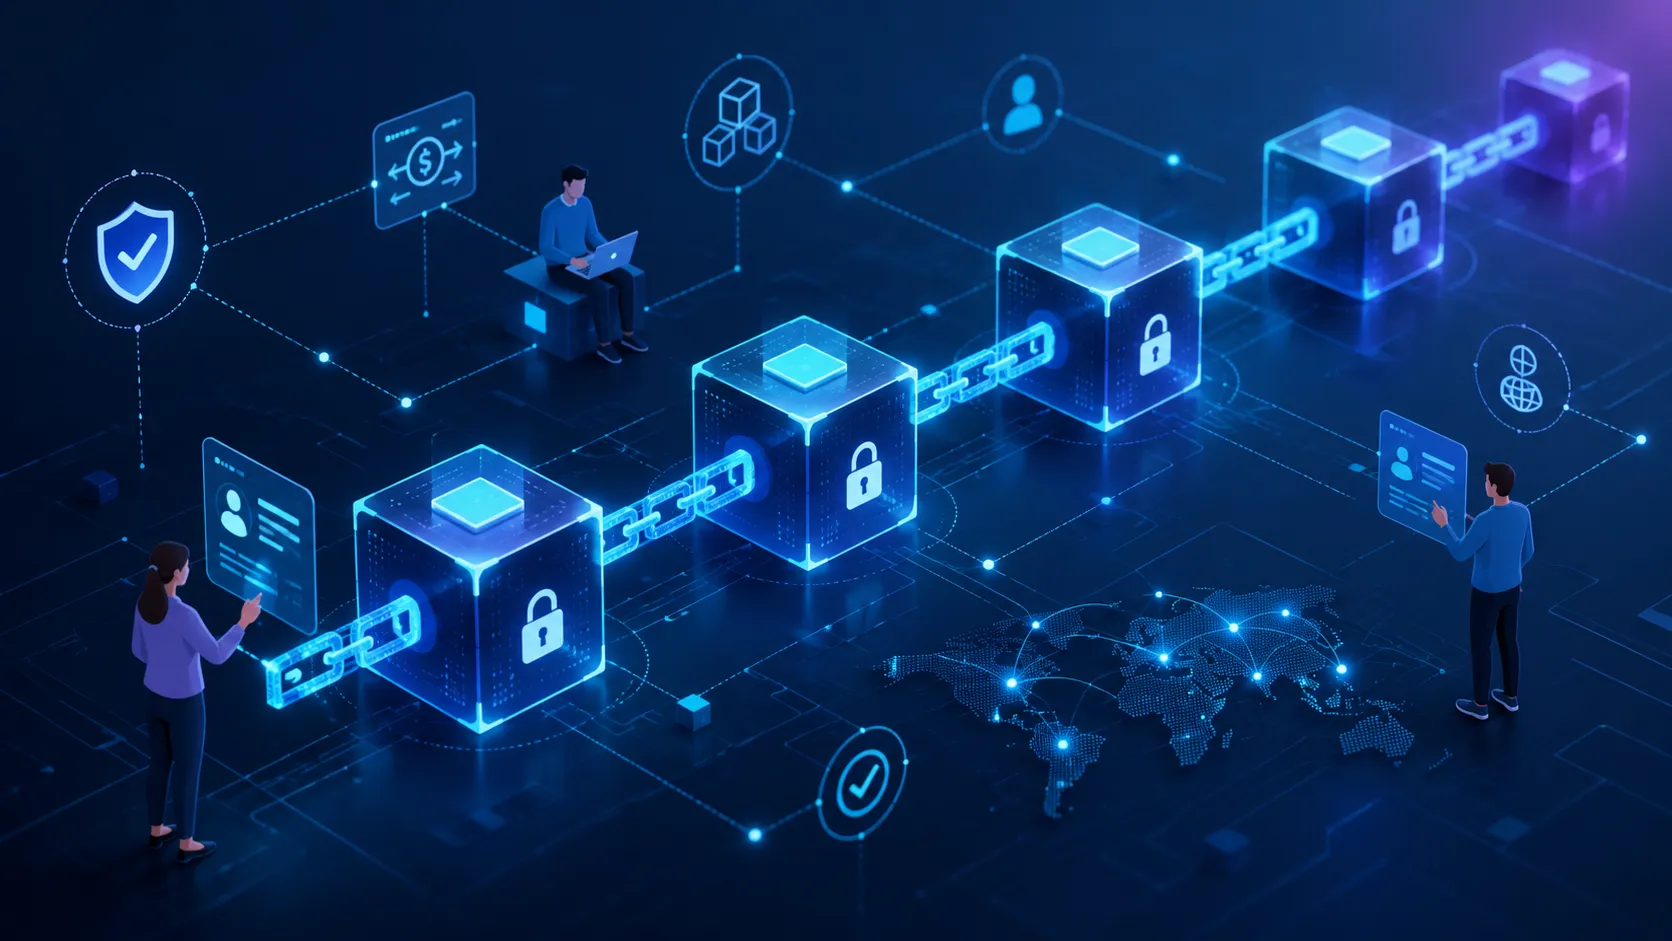
Information is grouped into digital containers known as blocks. Each new block is connected to the block that came before it. Over time, these connected blocks form a continuous chain, which is why the technology is called blockchain.
A Simple Example of How Blockchain Works
Imagine a village where ten business owners regularly lend money to one another. At first, they choose one person to record every transaction in a notebook. The notebook may say that Rahim gave Karim 500 dollars, Karim gave Jamal 200 dollars, and Jamal later returned 100 dollars to Rahim.
This system works as long as the person responsible for the notebook remains honest and careful. However, several problems can occur. The person controlling the notebook might secretly change a record. The notebook might be damaged, stolen, or lost. The owner could also accidentally record the wrong amount.
To solve this problem, the business owners decide that everyone should keep an identical copy of the notebook. Whenever a new transaction happens, the group checks the details. If everyone agrees that the transaction is valid, the new information is added to every copy.
Suppose one person secretly changes a transaction in their own copy. That altered copy will no longer match the other nine copies. The group can compare the records and identify which version is incorrect. A blockchain follows a similar principle. Instead of paper notebooks, it uses computers, software, network rules, and cryptography.
Understanding Blocks
A block is a digital container that stores information. The exact information inside a block depends on the blockchain, but a typical block may contain transaction details, the time the block was created, a reference to the previous block, information about the miner or validator, and other data required by the network.
A block can hold a limited amount of information. When enough valid transactions have been collected, the block is checked according to the rules of the blockchain. Once the network accepts it, the block is added to the existing chain.
How Blocks Are Connected
Every new block normally contains a reference to the previous block. This reference is created using something called a hash. A hash works like a unique digital fingerprint. It is created by passing information through a mathematical hashing algorithm.
The same information will normally produce the same hash. However, even the smallest change in the original information produces a completely different result. For example, the sentences “Rahim sent Karim 500” and “Rahim sent Karim 501” would produce different hashes because one number has changed.
When a new block is created, it includes the hash of the previous block. This creates a connection between the two blocks. If someone changes information inside an old block, that block’s hash will also change. The next block will still contain the original hash, which means the connection between the blocks will no longer match. This makes unauthorized changes easier for the network to detect.
What Is a Node?
A node is a computer or device connected to a blockchain network. Not every node performs exactly the same job. Some nodes store a complete copy of the blockchain, while others store only part of it. Depending on the network, nodes may verify transactions, share information, check blocks, create new blocks, or confirm that everyone is following the same rules.
A public blockchain may have thousands of nodes operating in different countries. Because the records are distributed across many devices, the network does not necessarily depend on one server. If one node goes offline, other nodes may continue operating and sharing information.
What Is a Blockchain Transaction?
A transaction is an action that is submitted to the blockchain network. The word transaction often makes people think only about sending cryptocurrency. However, a blockchain transaction can represent many different actions.
It may involve transferring a digital token, using a smart contract, creating an NFT, recording ownership, submitting information to an application, or interacting with a decentralized platform. Suppose Rahim sends one digital token to Karim. That action is considered a transaction.
However, creating a transaction does not mean it immediately becomes a permanent part of the blockchain. The network must first receive, verify, and approve it.
How a Blockchain Transaction Works
Imagine that Alice wants to send one cryptocurrency token to Bob. Alice begins by opening her cryptocurrency wallet. She enters Bob’s wallet address, chooses the amount she wants to send, and reviews the required transaction fee.
A wallet address is similar to a bank account number in the sense that it can be used to receive assets. However, it belongs to a blockchain network rather than a traditional banking system.
After entering the information, Alice signs the transaction using her private key. The digital signature proves that Alice authorized the transaction and that the details were not changed after she signed it. It also shows that she controls the blockchain account connected to the assets.
Alice’s private key must remain secret. Anyone who gains access to it may be able to control her wallet and transfer her assets.
Once the transaction has been signed, Alice’s wallet broadcasts it to the blockchain network. Broadcasting means that the transaction is shared with connected nodes. The nodes then examine the transaction. They may check whether Alice’s signature is valid, whether she has enough balance, whether the assets have already been spent, whether the transaction follows the network rules, and whether its format is correct.
If the transaction fails these checks, the network rejects it. If the transaction is valid, it is placed with other valid transactions waiting to be included in a block.
A miner, validator, or another type of block producer collects these transactions and creates a proposed block. The exact process depends on the consensus system used by the blockchain. The network then verifies the new block. Nodes check that its transactions are valid, its connection to the previous block is correct, and the block was created according to the protocol.
Once accepted, the block is added to the blockchain. Nodes update their records, and Alice’s transaction to Bob becomes part of the transaction history. As more blocks are added after it, the transaction receives additional confirmations. More confirmations generally make the transaction increasingly difficult to reverse or replace.
Public Keys and Private Keys
Blockchain wallets rely on cryptographic keys. The two most important types are public keys and private keys.
A private key is a secret digital key that allows someone to control a blockchain account. It can be used to sign transactions, authorize activity, and prove control over digital assets. A private key is often more important than a normal password. In many blockchain systems, losing the private key or recovery phrase can result in permanent loss of access. There may be no company, bank, or support team capable of restoring the account.
A public key is mathematically created from the private key. It can be shared publicly. In many blockchain systems, a wallet address is created from the public key.
A simple comparison can be made with email. An email address can be shared so other people can send messages, but the password must remain private. In the same way, a wallet address can be shared so others can send assets, but the private key must never be shared.
Where Cryptocurrency Is Actually Stored
Many beginners believe that cryptocurrency is stored inside a wallet application. That is not exactly how it works.
The blockchain stores the ownership records. The wallet stores or manages the keys that allow the user to access and control those assets. A wallet helps users view balances, sign transactions, manage keys, and communicate with blockchain networks.
This explains why a wallet can often be recovered on another device using a recovery phrase. The cryptocurrency did not physically move from one phone or computer to another. The assets remained recorded on the blockchain. The recovery phrase simply restored access to the keys connected to those assets.
What Is a Consensus Mechanism?
A blockchain network may not have one central authority deciding which transactions are valid. This creates an important challenge. The network needs a reliable method for agreeing on the correct version of the blockchain.
That method is called a consensus mechanism. Consensus means agreement. A consensus mechanism is a collection of rules that helps network participants agree on valid transactions and determine which block should be added next.
Different blockchains use different consensus mechanisms. Two of the most widely known systems are Proof of Work and Proof of Stake.
Proof of Work
Bitcoin uses a consensus mechanism called Proof of Work. In this system, miners use computing power to compete in solving a mathematical problem. The miner who finds a valid solution may earn the opportunity to propose the next block.
Other nodes verify the proposed block. If the transactions and block information follow the network rules, the block is added to the blockchain. The successful miner may receive newly created cryptocurrency and transaction fees as a reward.
Proof of Work can provide strong network security because attacking the blockchain may require enormous amounts of computing power and electricity. However, this energy use is also one of the system’s main criticisms.
Proof of Stake
Proof of Stake uses validators instead of traditional miners. Validators lock a certain amount of cryptocurrency in the network. This locked amount is called a stake.
According to the rules of the blockchain, a validator may be selected to propose or verify a new block. Validators have a financial reason to behave honestly because their staked assets may be at risk.
If a validator deliberately breaks the rules, part of the stake may be taken away. This penalty is commonly known as slashing. Proof of Stake generally requires less energy than Proof of Work because participants are not constantly competing through energy intensive calculations.
Why Blockchain Is Considered Secure
Blockchain security does not come from one feature. It is created through a combination of cryptography, distributed record keeping, consensus rules, and economic incentives.
Digital signatures help prove who authorized a transaction. Without the correct private key, creating a valid signature is extremely difficult. The network may store information across many nodes rather than one central server. This means the failure of one computer does not necessarily stop the complete network.
Hashes connect each block to the block before it. Changing an old record can create inconsistencies throughout the chain. Consensus rules prevent one participant from adding any transaction they want. The rest of the network checks whether the transaction and block follow the protocol.
Many networks also reward honest participants and punish dishonest behaviour. A miner or validator that attempts to cheat may lose rewards, money, computing resources, or staked assets.
Can Blockchain Data Be Changed?
People often say that blockchain information can never be changed. This statement is too simple.
A more accurate explanation is that changing confirmed historical data on a secure and widely distributed blockchain can be extremely difficult and expensive. If someone changes an old block, its hash will change. The connection with the following block will no longer match. Later blocks may also need to be recreated.
At the same time, other nodes will still have copies of the original blockchain. An attacker may need to control a large portion of the network’s computing power or validation influence to convince the network to accept the altered version.
However, not every blockchain has the same level of security. A small network with only a few participants may be easier to manipulate than a large and widely distributed public blockchain. Blockchain should therefore be described as tamper resistant rather than magically impossible to change.
Is Blockchain Anonymous?
Most public blockchains are not completely anonymous. Networks such as Bitcoin and Ethereum usually display transaction information publicly. However, they normally display wallet addresses rather than real names. This system is known as pseudonymity.
A blockchain explorer may show that one wallet address sent funds to another address. The public can see the transaction amount, time, and addresses, but they may not immediately know who owns those addresses.
However, a wallet address can sometimes be connected to a real identity. This may happen when the address is used with a cryptocurrency exchange that requires identity documents, published on a website, connected to a public profile, or included in other identifiable records.
Once the owner of an address is identified, their previous public transactions may also become easier to trace.
What Is a Blockchain Explorer?
A blockchain explorer is a website or application that allows users to view public blockchain information. It functions like a search engine for blockchain data.
A user can enter a transaction number, wallet address, block number, or smart contract address to view related information. The explorer may display the transaction status, sender address, receiver address, amount, transaction fee, block number, number of confirmations, smart contract details, and the time the block was created.
Blockchain explorers are useful for checking whether a transaction has been received and confirmed.
What Is a Gas Fee?
Blockchain transactions require computing and network resources. On networks such as Ethereum, users pay a fee to use those resources. This fee is commonly called a gas fee.
The size of the fee may depend on network traffic, transaction complexity, the amount of computation required, the quantity of data being processed, and the speed requested by the user.
A simple token transfer may cost less than interacting with a complicated smart contract. When many people try to use the network at the same time, fees may increase because users are competing for limited block space.
What Is a Smart Contract?
A smart contract is a program that runs on a blockchain. It contains predefined rules and can perform actions when specific conditions are met.
Imagine a smart contract that says a digital ticket should be transferred to a customer once the required payment has been received. When the blockchain confirms the payment, the contract can automatically send the ticket without requiring an employee to process the order manually.
Smart contracts can be used to create tokens, NFTs, voting systems, lending platforms, escrow services, subscriptions, decentralized exchanges, digital identity systems, and supply chain applications.
However, smart contracts cannot automatically know everything happening outside the blockchain. For example, a smart contract cannot independently know whether it is raining, whether a flight has been cancelled, or whether a shipment has arrived.
To receive information from the outside world, the contract may depend on a service called an oracle. The quality and security of that external data are extremely important. A smart contract may execute perfectly but still produce the wrong result if the information provided to it is false.
Are Bitcoin and Blockchain the Same?
Bitcoin and blockchain are not the same thing. Blockchain is the underlying technology and record keeping system. Bitcoin is a digital currency and payment network that uses blockchain technology.
The relationship can be compared to the internet and email. The internet is a technology. Email is one application built using that technology. In the same way, blockchain is a technology, while Bitcoin is one of its applications.
Ethereum, Solana, Polygon, and many other networks also use blockchain technology. Each network has its own design, fees, applications, consensus system, and security model.
Is Blockchain Only Used for Cryptocurrency?
Cryptocurrency is the most famous blockchain use case, but blockchain can be applied in other areas. It can support digital payments between users in different countries, especially when traditional payment systems are expensive or difficult to access.
Businesses may use blockchain to record how products move through a supply chain. Information about manufacturing, inspection, transportation, and delivery can be added to a shared record.
Blockchain may also be used in digital identity systems that give users greater control over their credentials and personal information. In healthcare, it may help manage access permissions and verify records. However, highly sensitive medical information should not usually be stored directly on a public blockchain because public records may be difficult to remove.
Blockchain based voting systems may improve transparency and allow results to be verified. Nevertheless, voting also involves complex challenges related to identity, privacy, device security, accessibility, coercion, and election law.
Property ownership and transfer records may also be recorded through blockchain systems. Schools and universities can issue digital certificates that are easier for employers and institutions to verify.
NFTs use blockchain to record ownership of digital art, game items, tickets, memberships, collectibles, and other virtual assets. Decentralized finance applications can offer services such as lending, borrowing, token exchanges, staking, liquidity pools, and digital payments.
These examples do not mean blockchain is always the best solution. Each use case must be evaluated carefully.
Public, Private, and Consortium Blockchains
Not every blockchain is completely open to the public. A public blockchain is generally accessible to anyone. People may be able to view transactions, submit transactions, run nodes, use applications, and participate according to the network’s rules. Bitcoin and Ethereum are common examples of public blockchains.
A private blockchain is controlled by one organization or a limited group. Users normally need permission before they can access the network or add information. Private blockchains may be used for internal business processes, record sharing, or communication between approved departments.
A consortium blockchain is controlled by several approved organizations rather than one company. For example, a group of banks, shipping companies, hospitals, or supply chain businesses might jointly operate a shared blockchain network.
The word blockchain does not automatically mean that a system is decentralized. Some blockchains are widely distributed, while others remain highly controlled.
Blockchain Compared With a Traditional Database
A traditional database is usually controlled by one company, government department, or organization. The authority operating the database can add information, edit records, delete data, manage user access, correct mistakes, and shut down the server.
A blockchain can distribute record keeping across several participants. It may provide shared records, transparency, digital ownership, automation, and resistance to unauthorized changes.
However, traditional databases also have important advantages. They are often faster, cheaper, easier to manage, easier to update, and more suitable for private information. They may also provide better account recovery and support applications that need extremely high performance.
Blockchain is not automatically better than a traditional database. The correct choice depends on the problem being solved.
When Blockchain May Be Useful
Blockchain may be useful when several organizations need to share the same records but do not fully trust one another. It can also be valuable when historical information should be difficult to change, when transparency is important, when users need to control digital assets, or when dependence on one central authority should be reduced.
Smart contracts may also be useful when shared rules need to be executed automatically. However, blockchain may not be necessary when one company already controls the complete system, when information must be edited or deleted regularly, or when extremely high speed is required.
It may also be unnecessary when a normal database can solve the problem more simply and at a lower cost. A skilled blockchain developer should understand not only how to build blockchain applications, but also when blockchain should not be used.
The Main Advantages of Blockchain
One important advantage of public blockchains is transparency. Transactions can often be viewed and verified by anyone. Blockchain can also provide strong resistance to unauthorized data changes through cryptography, distributed records, and consensus rules.
Decentralization can reduce dependence on one company, authority, or server. The movement of assets and information can be traced through the transaction history, which may improve accountability.
Smart contracts allow certain activities to be automated according to predefined rules. Many public blockchain networks can be accessed from anywhere with an internet connection. Blockchain also gives users the ability to control digital assets through cryptographic keys without depending completely on a traditional financial institution.
The Limitations of Blockchain
Blockchain is powerful, but it is not a perfect solution. Some networks can process only a limited number of transactions within a given period. This creates scalability problems when large numbers of people try to use the system.
Transaction fees may also become expensive during periods of heavy network traffic. Proof of Work blockchains can consume significant amounts of electricity.
User mistakes can be difficult to correct. Sending assets to the wrong wallet address may result in permanent loss because there may be no refund option. Losing a private key or recovery phrase can also permanently remove access to assets.
Smart contracts may contain programming errors. Because they can control valuable assets, even a small vulnerability may have serious consequences.
Blockchain regulations differ from one country to another and can change over time. Developers and businesses must understand the legal requirements in the regions where they operate.
Privacy is another major concern. Public transactions may remain visible for a very long time. Storing large files directly on a blockchain can also be expensive and inefficient. In many projects, only a reference or hash is stored on the blockchain, while the actual file is kept elsewhere.
Can Blockchain Be Hacked?
The phrase “blockchain hack” can describe many different types of incidents. In many cases, the main blockchain protocol is not directly broken.
Attackers may target cryptocurrency exchanges, user wallets, private keys, phishing websites, smart contracts, bridges, frontend applications, centralized servers, admin accounts, oracles, and other connected systems.
For example, a fake website may ask a user to enter their recovery phrase. If the user provides it, the attacker can gain control of the wallet. This does not mean the blockchain’s cryptography was defeated. It means the attacker stole the information needed to control the account.
A smart contract may also contain a programming vulnerability that allows an attacker to withdraw funds or manipulate the application. Blockchain security must therefore cover the entire system, including the blockchain, applications, websites, wallets, keys, servers, contracts, and users.
What Is a 51 Percent Attack?
In a Proof of Work blockchain, a 51 percent attack may occur when one person or group controls most of the network’s mining power. The attacker may try to reorganize recent blocks, reverse their own transactions, perform double spending, or prevent certain transactions from being confirmed.
However, controlling the majority of mining power does not normally allow the attacker to take assets directly from another person’s wallet without that person’s private key.
A 51 percent attack can be extremely expensive on a large blockchain because the attacker would need enormous computing resources. Smaller networks with less mining power may be more vulnerable.
What Is Double Spending?
Digital information can be copied easily. This creates a serious problem for digital money because the same digital asset should not be spent more than once.
Imagine that Rahim owns one digital coin and attempts to send the same coin to both Karim and Jamal. The blockchain uses transaction order, balance checks, consensus rules, and network validation to determine which transaction is valid.
Once the valid transaction is confirmed, the second attempt is rejected. This is how blockchain helps solve the double spending problem without requiring every transaction to be approved by one central bank or company.
What Is Inside a Block?
The exact structure of a block depends on the blockchain. A block may contain a block number, a list of transactions, the previous block’s hash, the current block’s hash, a timestamp, validator or miner information, a nonce, a Merkle root, and other information required by the protocol.
The previous block hash connects the block to the existing chain. The timestamp records when the block was created. The transaction list contains the activity included in the block. The remaining information helps nodes verify that the block was produced correctly.
What Is a Merkle Root?
A block may contain hundreds or thousands of transactions. Creating and checking each transaction individually every time could be inefficient.
To solve this problem, transaction hashes can be combined together in several stages until one final hash is produced. This final hash is called a Merkle root. The Merkle root allows a network or application to verify efficiently whether a particular transaction belongs to a specific block.
What Is the Genesis Block?
The first block in a blockchain is called the genesis block. Because it is the first block, it does not have a previous block.
The genesis block serves as the starting point of the blockchain. Every future block is connected to it either directly or through the blocks that come before it.
What Is a Blockchain Fork?
A fork can occur when blockchain rules change or when the network temporarily produces two possible versions of its transaction history.
A soft fork introduces new rules that may remain compatible with older versions of the software. A hard fork introduces rules that are not compatible with the previous version.
In some cases, a hard fork can divide one blockchain into two separate networks. Participants must then decide which set of rules they want to follow.
Layer 1 and Layer 2 Networks
A Layer 1 is the main blockchain network. Bitcoin, Ethereum, and Solana are examples of Layer 1 networks.
A Layer 2 is a system built to improve the speed, cost, or scalability of a Layer 1 blockchain. It may process some activity separately and later submit the results to the main blockchain.
This approach can reduce fees, increase transaction capacity, and move some computation away from the main network. Common scaling methods include optimistic rollups, zero knowledge rollups, and payment channels.
Common Misunderstandings About Blockchain
One common misunderstanding is that blockchain and Bitcoin are the same. Bitcoin is one application of blockchain technology, not the technology itself.
Another misunderstanding is that all blockchain information is private. In reality, data on a public blockchain is generally visible to everyone.
Some people believe blockchain applications cannot be hacked. Although the blockchain protocol may be secure, smart contracts, wallets, websites, servers, bridges, and user accounts can still contain vulnerabilities.
Blockchain transactions are not always free. Many networks require users to pay transaction fees. Cryptocurrency is also not physically stored inside a wallet application. Ownership is recorded on the blockchain, while the wallet manages the keys needed to control the assets.
Blockchain cannot replace every database. Traditional databases are often faster, cheaper, simpler, and more suitable for many applications. Smart contracts also do not automatically know what is happening in the outside world. They may need external data providers or oracles.
A Real World Supply Chain Example
Imagine a company that exports mangoes. The mangoes are first grown by a farmer. They are then delivered to a collection centre, inspected for quality, prepared by an exporter, transported by a shipping company, received by an importer, and finally sold in a store.
Important information from each stage could be recorded in a shared blockchain system. Approved participants could add details about where the mangoes were grown, when they were collected, whether they passed inspection, which shipment transported them, and which importer received them.
A customer might scan a QR code on the package and view some of this information. However, blockchain cannot automatically prove that the original information was true.
If someone enters false information at the beginning, the blockchain may permanently store that false information. Blockchain can make records difficult to change, but it cannot guarantee that every piece of information entered into the system was accurate. This problem is commonly described as garbage in, garbage out.
Who Controls a Blockchain Network?
The answer depends on the type of blockchain. A public blockchain may involve core developers, node operators, validators, miners, token holders, application developers, foundations, community members, and regular users.
Some participants develop and update the software. Others operate nodes, verify transactions, build applications, provide infrastructure, or participate in governance.
A private blockchain may be controlled by one company. A consortium blockchain may be jointly controlled by several organizations.
Blockchain does not always mean there is no control. It means that control can be distributed in different ways depending on the design of the network.
What Does a Blockchain Developer Do?
A blockchain developer does much more than create cryptocurrency. Blockchain developers may build smart contracts, tokens, NFT platforms, payment gateways, wallet integrations, decentralized applications, decentralized finance protocols, blockchain backends, Web3 interfaces, indexing services, event processing systems, governance platforms, and infrastructure tools.
They may also test smart contracts, improve gas efficiency, perform security reviews, build applications that work across several networks, and manage blockchain data.
A strong blockchain developer needs knowledge of programming, security, networking, databases, system architecture, cryptography, and blockchain economics. Writing a smart contract is only one part of the job. Developers must also understand how users interact with the application and how the complete system can be protected.
How a Beginner Can Start Learning Blockchain
A beginner should first become comfortable with the basic ideas of blocks, transactions, hashes, nodes, wallets, keys, and consensus.
The next step is to use a blockchain instead of only reading about it. A learner can create a wallet and experiment on a test network. Test network tokens usually do not have real financial value, which makes them useful for practice.
After making a test transaction, the learner can open a blockchain explorer and examine the sender, receiver, fee, block number, confirmation count, and transaction status.
Programming knowledge becomes important for anyone who wants to become a blockchain developer. For Ethereum development, technologies such as JavaScript, TypeScript, Solidity, React, Next.js, Ethers.js, Viem, Hardhat, and Foundry can be useful.
Beginners should start with small projects. A simple token, voting contract, donation application, NFT application, token vesting contract, or multi signature wallet can provide valuable practice.
Security should be studied from the beginning. Important topics include reentrancy, access control, front running, oracle manipulation, signature replay attacks, upgradeable contract risks, private key protection, and precision errors.
A blockchain application may control real financial assets, so security cannot be treated as an optional final step.
Do You Need Cryptocurrency to Use Blockchain?
Not every blockchain system requires cryptocurrency. Private or consortium blockchains may operate without a publicly traded token.
However, many public blockchain networks use a native cryptocurrency to pay transaction fees, reward validators or miners, and support network security.
Who Owns a Blockchain?
A public blockchain may not have one owner. It may be developed and operated by a combination of developers, node operators, validators, miners, foundations, companies, and community members.
A private blockchain may be owned or controlled by one organization. Ownership and control depend on the structure of the network.
Can a Blockchain Be Shut Down?
A widely distributed public blockchain can be difficult to shut down because nodes may continue operating in many countries. Closing one company or blocking one server may not stop the complete network.
A small or highly centralized blockchain may be easier to stop because it depends on fewer operators or servers.
Can a Cryptocurrency Transaction Be Reversed?
A confirmed blockchain transaction is normally difficult or impossible to reverse. The receiver may voluntarily return the assets, but the network usually does not provide a simple refund button.
Users should always check the wallet address, network, token, and amount carefully before confirming a transaction.
Can Blockchain Data Be Deleted?
Confirmed data on a public blockchain is generally difficult to remove. This creates serious privacy and legal concerns.
Developers should avoid placing private personal information directly on a public blockchain unless there is a clear and legally appropriate reason. In many systems, private data is stored outside the blockchain, while only a hash or reference is recorded on the chain.
Can Blockchain Work Without the Internet?
A transaction can sometimes be created and signed while a device is offline. However, an internet or network connection is normally required to broadcast the transaction to the blockchain and receive confirmation.
The blockchain network itself also depends on communication between nodes.
Will Blockchain Replace Banks?
Nobody can say with certainty how much of the financial system blockchain will eventually change. Blockchain may improve or transform payments, settlements, lending, asset ownership, and international transfers.
However, banks provide many services beyond recording transactions. They offer lending, customer support, compliance, identity verification, fraud prevention, risk management, and account recovery.
Traditional finance and blockchain based finance are likely to continue developing alongside each other.
Final Thoughts
Blockchain is a shared digital record system in which information is grouped into blocks and connected through cryptographic hashes.
When a user creates a transaction, it is signed with a private key and broadcast to the network. Nodes examine the transaction and check whether it follows the rules. Valid transactions are collected into a block. The network uses a consensus mechanism to verify the block before adding it to the existing chain.
Blockchain can provide transparency, shared records, digital ownership, automation, traceability, and reduced dependence on central authorities.
However, it also has limitations involving scalability, transaction fees, privacy, regulation, storage costs, smart contract vulnerabilities, key management, and user mistakes.
Blockchain should not be treated as a magical solution for every problem. Before using it in a project, the most important question is whether the problem genuinely requires blockchain or whether a traditional database would provide a simpler and more efficient solution.
Understanding blockchain is not only about learning how blocks and transactions work. It is also about recognising where the technology creates real value, where it introduces unnecessary complexity, and how it can be used responsibly.